A Flexible Path to Homeownership
An FHA loan can make buying a home more accessible by offering a low down payment and flexible qualification guidelines. Insured by the Federal Housing Administration, FHA loans are designed to help qualified buyers finance a primary residence through an FHA-approved lender.
You do not have to be a first-time homebuyer or meet a specific income limit to use an FHA loan. Whether you are purchasing your first home in Corpus Christi or making your next move elsewhere in Texas, FHA financing may provide a practical path forward.
Benefits of an FHA Loan
FHA loans offer several features that may help make homeownership more attainable:
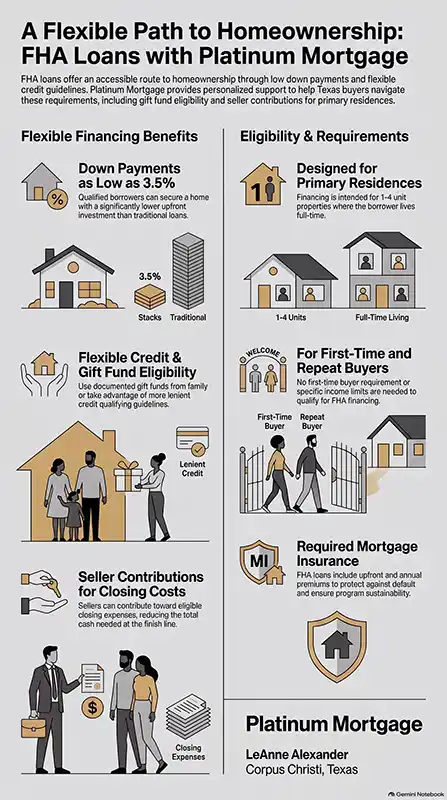
- Down payments as low as 3.5% for qualified borrowers
- Gift funds from eligible sources
- Seller contributions toward eligible closing costs
- Competitive interest-rate options
Every borrower and property must meet applicable FHA and lender requirements.
A Down Payment as Low as 3.5%
Qualified borrowers may be able to purchase a home with a down payment of just 3.5% of the purchase price. The amount required depends on factors such as credit history, income, existing debt, available funds and the lender’s qualification requirements. Gift funds from an eligible family member or another permitted source may be used toward the down payment or eligible closing expenses when properly documented.
Seller Contributions Can Help With Closing Costs
In addition to the down payment, buyers should prepare for expenses such as appraisal fees, title charges, prepaid taxes, homeowners insurance and other closing costs. FHA guidelines allow a seller or another interested party to contribute toward eligible closing costs, prepaid expenses and discount points, subject to program limits. Seller contributions generally cannot replace the buyer’s required minimum down payment, but they can reduce the amount of additional money needed at closing.
FHA Loans Are for a Primary Residence
An FHA loan is intended for a home you plan to occupy as your primary residence. It is not used to purchase a vacation home or a property that will be held solely as an investment.
Eligible properties may include certain:
- Single-family homes
- One to four unit family properties
- Manufactured homes
Understanding FHA Mortgage Insurance
FHA loans require mortgage insurance, which helps protect the lender if the borrower defaults. This includes an upfront mortgage insurance premium and an annual premium divided among the monthly mortgage payments.
Mortgage insurance affects the total cost of the loan, so it is important to compare the complete monthly payment and long-term costs—not only the down payment. A review of both FHA and conventional loan options can help determine which structure better fits your finances and homeownership goals.
Is an FHA Loan Right for You?
An FHA loan may be worth considering if you:
- Want to purchase a primary residence with a smaller down payment
- Plan to use eligible gift funds
- Want to explore seller assistance with closing costs
FHA financing is only one possible route. Your income, debts, credit profile, savings, property choice and future plans should all be considered before selecting a mortgage.
FHA Loan Frequently Asked Questions
No, both first-time and repeat homebuyers may qualify for an FHA loan.
FHA loans are not generally restricted to low- or moderate-income borrowers. Applicants must demonstrate sufficient qualifying income and satisfy the lender’s credit, debt and underwriting requirements.
Yes, gift funds from an eligible and properly documented source may be used toward the down payment or certain closing expenses.
A seller may contribute toward eligible closing costs, prepaid expenses and discount points within FHA limits. The contribution cannot generally be used to satisfy the buyer’s minimum required investment.
Yes, FHA loans generally include both upfront and annual mortgage insurance premiums.
An FHA loan is intended for a primary residence. A qualifying two- to four-unit property may be eligible when the borrower occupies one of the units as a primary residence.
Explore Your FHA Loan Options
You do not have to determine the right mortgage on your own. Platinum Mortgage can review your homebuying goals, explain the costs and requirements of FHA financing, and help you compare it with other available home loan options.
Contact Platinum Mortgage to discuss your plans and find out whether an FHA loan may be a good fit for your next home.
All loans are subject to application, credit approval, property approval and applicable underwriting requirements. Program terms, interest rates, loan limits and eligibility requirements are subject to change. This information is for general educational purposes and is not a commitment to lend.