Purchase the Home and Finance the Improvements
The right home may need a new kitchen, updated flooring, major repairs or a complete transformation. A renovation loan can combine the home purchase and eligible improvement costs into one financing plan. Instead of paying for renovations separately after closing, qualified buyers may be able to include approved project costs in their mortgage. Depending on the borrower, property and program availability, renovation financing may be offered through FHA, VA or conventional loan options.
How a Renovation Loan Works
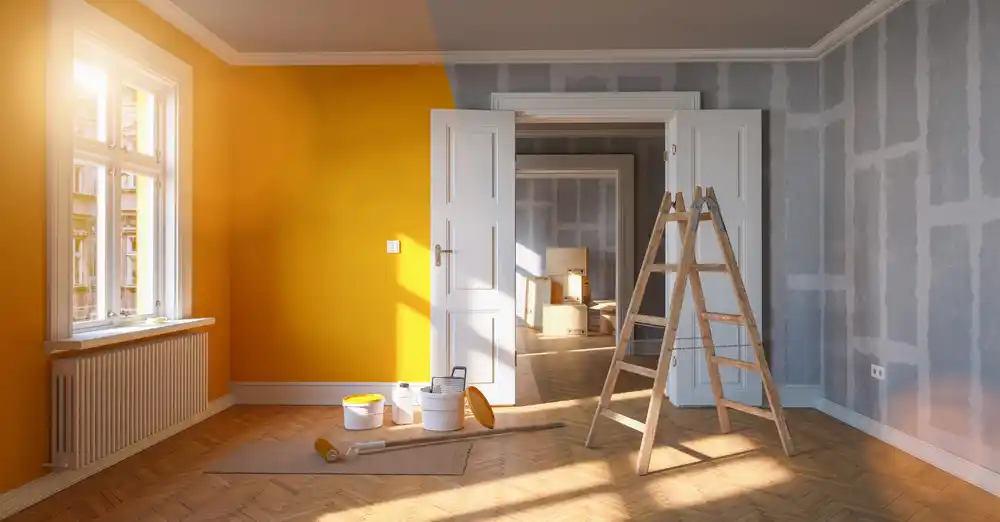
The renovation plans begin before closing. The lender generally reviews the proposed scope of work, contractor estimates and required documentation as part of the loan approval.
The process typically includes:
- Select a property and identify the improvements.
- Obtain detailed plans and contractor estimates.
- Complete an appraisal based partly on the anticipated finished condition.
- Close on the home and renovation financing.
- Hold the renovation funds in a designated account.
- Release funds as approved work is completed and verified.
Requirements vary based on the loan program and the size and type of renovation.
What Improvements May Be Eligible?
Depending on the program, eligible projects may include:
- Kitchen and bathroom remodeling
- Roofing, HVAC, plumbing or electrical work
- Flooring, painting and interior updates
- Energy-efficiency improvements
- Accessibility modifications
- Other permanent improvements to the property
Luxury items and improvements that are not permanently connected to the property may be restricted.
Renovation Financing Options
FHA Renovation Financing
An FHA renovation loan may help qualified borrowers purchase and improve an eligible primary residence. Limited and Standard FHA 203(k) programs accommodate different project sizes and types.
VA Renovation Financing
Eligible Veterans, service members and surviving spouses may have access to VA-backed renovation financing for a qualifying primary residence. Program availability and property requirements vary by lender.
Conventional Renovation Financing
A conventional renovation loan may offer flexible improvement options for eligible borrowers and properties. Down-payment, occupancy and project requirements depend on the selected program.
Planning Matters
Renovation financing requires more preparation than a standard home purchase. Contractor approval, detailed estimates, permits, inspections, contingency funds and completion deadlines may all be part of the process.
Starting the conversation before making an offer can help you understand the requirements and determine whether the property and planned improvements are a good match for the available financing.
Renovation Loan Frequently Asked Questions
Yes, an eligible renovation program may combine the purchase price and approved improvement costs into one loan.
No, the project is generally planned and approved before closing, but work begins after the purchase has closed and the lender has authorized construction.
Depending on the program, you may select a contractor who satisfies the lender’s licensing, insurance, experience and documentation requirements.
Renovation funds are generally held in a designated account and released through draws as approved work is completed and inspected.
The appraisal may consider the home’s anticipated value after the approved renovations are completed. The program’s loan limits and calculation requirements still apply.
Bring Your Vision Within Reach
A home that needs work may still have everything required to become your dream home. Platinum Mortgage can help you compare renovation programs, understand the process and determine whether the purchase and proposed improvements may qualify.
Contact Platinum Mortgage to discuss the property and renovation plans before you make your offer.
All loans are subject to application, credit approval, property approval, appraisal and applicable underwriting requirements. Renovation programs, eligible improvements, contractor requirements, rates, fees and terms vary by lender and are subject to change. This information is for general educational purposes and is not a commitment to lend.