Flexible Financing for More Types of Homes
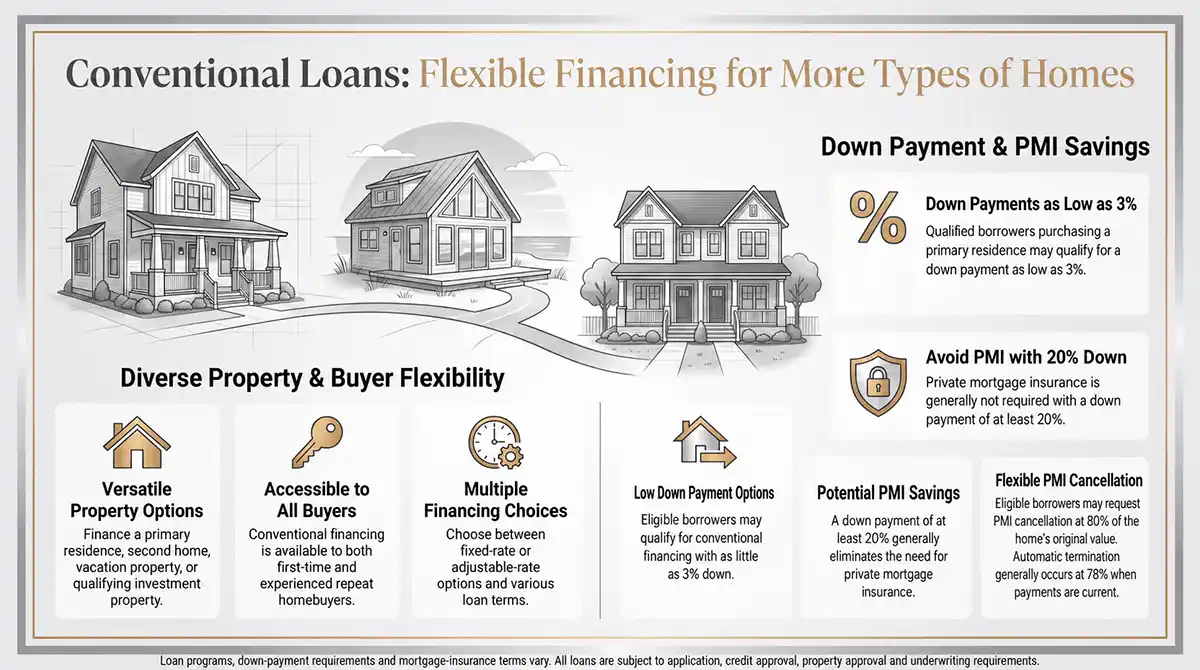
A conventional loan provides flexible financing for qualified buyers purchasing a primary residence, second home, vacation property or investment property. Conventional financing is available to both first-time and repeat homebuyers, with multiple down-payment and mortgage-insurance options. The right structure depends on your property plans, finances and long-term goals.
Benefits of a Conventional Loan
A conventional loan may offer:
- Financing for a primary residence
- Financing for an eligible second or vacation home
- Financing for qualifying investment properties
- Down-payment options as low as 3% for qualified borrowers
- Private mortgage insurance can be waived with a 20% down payment
- The ability to request PMI cancellation after meeting applicable requirements
Down-payment, credit, reserve and underwriting requirements vary by borrower, property type, occupancy and loan program.
Conventional Loan Down-Payment Options
You do not always need a 20% down payment to qualify for a conventional mortgage. Certain programs may allow eligible borrowers purchasing a primary residence to put down as little as 3%.
The minimum down payment depends on several factors, including:
- Whether you are a first-time or repeat buyer
- How you intend to use the property
Second homes and investment properties generally require larger down payments and may have additional reserve, credit and underwriting requirements.
Understanding Private Mortgage Insurance
Private mortgage insurance, commonly called PMI, may be required when a borrower finances a conventional home purchase with less than a 20% down payment. PMI protects the lender—not the homeowner—if the borrower defaults on the mortgage.
PMI can increase the monthly payment, but it may also allow a qualified buyer to purchase a home without waiting to save a full 20% down payment.
If you make a down payment of at least 20%, PMI is generally not required.
Can Conventional Mortgage Insurance Be Removed?
For certain mortgages secured by a primary residence, a homeowner may request PMI cancellation when the principal balance is scheduled to reach—or has been paid down to—80% of the home’s original value. The borrower must satisfy applicable requirements, which may include:
- Submitting a written cancellation request
- Being current on the mortgage
- Maintaining an acceptable payment history
- Having no disqualifying junior liens
- Providing evidence that the property’s value has not declined
For qualifying loans, PMI is generally scheduled to terminate automatically when the principal balance reaches 78% of the home’s original value, provided the borrower is current. Different rules may apply based on the loan, property, mortgage-insurance arrangement and applicable law. Your loan servicer determines whether the cancellation requirements have been satisfied.
Primary Residences, Second Homes and Investment Properties
One of the most significant advantages of conventional financing is the range of eligible occupancy types.
Primary Residence
A primary residence is the home you intend to occupy as your main residence. Eligible primary-residence borrowers generally have access to the widest range of down-payment and loan-program options.
Second or Vacation Home
Conventional financing may be used for an eligible second home or vacation property. The home must meet applicable occupancy requirements and cannot simply be represented as a second home when its actual purpose is rental or investment use.
Investment Property
A conventional loan may also finance a qualifying property purchased to generate rental income or hold as an investment. Investment-property financing typically has larger down-payment, reserve and qualification requirements than financing for a primary residence.
Is a Conventional Loan Right for You?
Conventional financing may be a good fit if you:
- Are purchasing your first or next primary residence
- Want to buy a second home or vacation property
- Are considering an investment-property purchase
- Want several down-payment options
- Want to avoid or eventually remove private mortgage insurance
- Would benefit from comparing multiple loan structures
A personalized review can help determine which loan option provides the right balance of upfront cost, monthly payment and long-term value.
Conventional Loan Frequently Asked Questions
No, conventional loans are available to both first-time and repeat homebuyers. Certain programs offer qualified first-time buyers down payments as low as 3%.
No, some eligible borrowers may qualify with a down payment as low as 3%. However, putting down less than 20% may require private mortgage insurance.
No, PMI is generally not required when the borrower makes a down payment of at least 20%. Other loan structures and lender-paid mortgage-insurance options may work differently.
Borrowers with certain eligible mortgages may request cancellation when the loan balance reaches 80% of the home’s original value and all applicable requirements are satisfied. PMI may automatically terminate at the scheduled 78% point when the borrower is current. Contact your loan servicer for the requirements governing your mortgage.
Yes, conventional financing may be used for an eligible second home or vacation property, subject to applicable occupancy, down-payment, reserve and underwriting requirements.
Yes, conventional loans can finance qualifying investment properties. These transactions typically require a larger down payment and additional financial reserves.
That depends on your credit, savings, property plans and long-term goals. Reviewing both options can reveal differences in upfront costs, mortgage insurance and monthly payments.
Explore Your Conventional Loan Options
The best mortgage is not simply the one with the lowest advertised down payment. It is the loan that fits your property, budget and plans for the future.
Platinum Mortgage can help you review conventional financing, compare it with other home loan options, and understand the costs and qualification requirements before you make a decision.
Contact Platinum Mortgage to discuss your homebuying plans and determine whether a conventional loan may be right for you.
All loans are subject to application, credit approval, property approval and applicable underwriting requirements. Program terms, interest rates, loan limits, mortgage-insurance requirements and eligibility guidelines are subject to change. This information is for general educational purposes and is not a commitment to lend.