A Home Loan Benefit Earned Through Service
A VA-backed home loan can help eligible Veterans, active-duty service members, members of the National Guard and Reserve, and certain surviving spouses purchase a home with favorable financing terms.
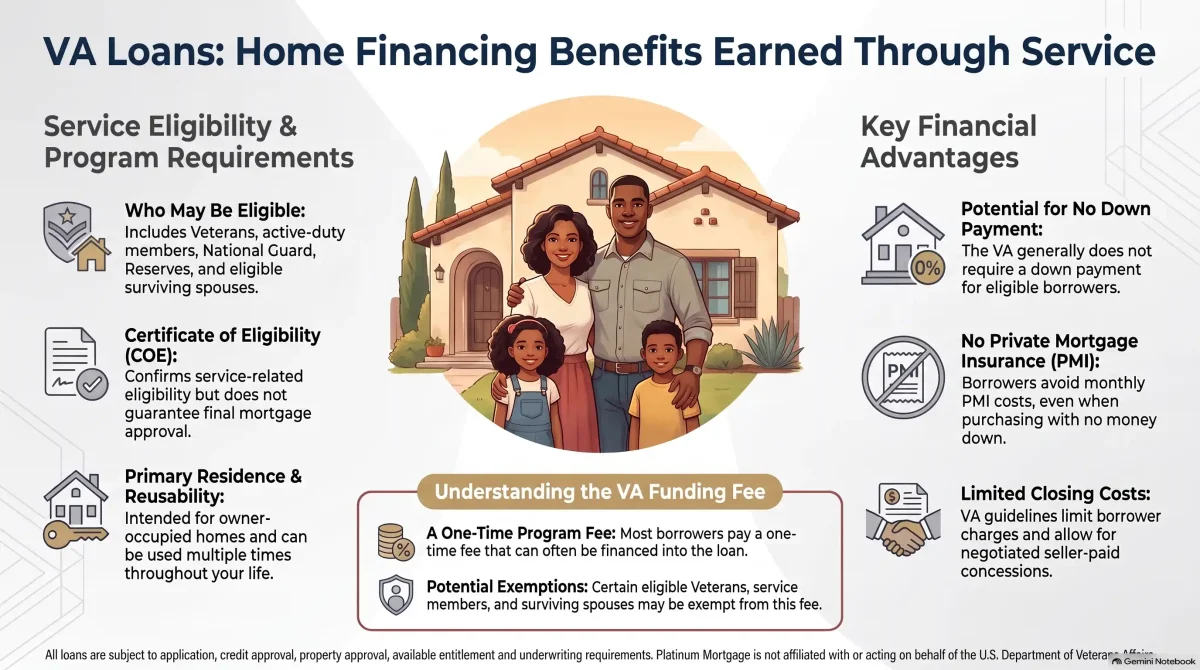
The program is administered by the U.S. Department of Veterans Affairs, but the mortgage is provided by a private lender. The VA guarantees a portion of the loan, allowing approved lenders to offer valuable benefits that may include no required down payment, no private mortgage insurance and limits on certain closing costs.
Platinum Mortgage is honored to help eligible military homebuyers understand and use the home loan benefits they have earned through service. To find out if you are eligible visit va.gov and request your Certificate of Eligibility.
Benefits of a VA Loan
A VA-backed purchase loan may offer:
- No down payment required by the VA
- No private mortgage insurance
- Limits on certain closing costs
- Seller-paid closing-cost options
- Seller concessions within VA guidelines
- Fixed-rate and adjustable-rate options
Although the VA generally does not require a down payment, a lender or the circumstances of a particular transaction may require one. Every borrower, property and loan must satisfy VA and lender requirements.
Who May Be Eligible for a VA Loan?
VA home loan eligibility is based on service history, duty status and other applicable requirements. Potentially eligible borrowers may include:
- Veterans
- Active-duty service members
- Current or former National Guard members
- Current or former Reserve members
- Certain surviving spouses
The length and character of service requirements vary. Eligibility for the VA home loan program does not automatically mean the loan will be approved. Applicants must also satisfy the lender’s credit, income, debt, occupancy and underwriting requirements.
Is a VA Loan Really Available With No Down Payment?
The VA itself generally does not require a down payment, and many eligible borrowers use VA financing to purchase a home without one. However, a down payment may be necessary in certain circumstances, such as when:
- The purchase price exceeds the VA-determined reasonable value
- The borrower has only partial entitlement available
- The lender requires one based on the transaction
- The borrower chooses to make a down payment to reduce the loan amount or funding fee
A no-down-payment loan does not mean the home purchase has no upfront expenses. Buyers may still need funds for earnest money, inspections, appraisal-related expenses, prepaid taxes, homeowners insurance and closing costs not paid by another party.
No Private Mortgage Insurance
VA-backed loans do not require private mortgage insurance, commonly called PMI. This can be especially valuable for eligible borrowers purchasing a home without a large down payment. VA loans may instead include a one-time VA funding fee. The amount can depend on the loan type, down payment, previous use of the VA home loan benefit and other factors. The funding fee may often be financed into the loan. Certain eligible Veterans, service members and surviving spouses may be exempt from the funding fee. The borrower’s COE and supporting VA documentation help determine exemption status.
Closing Costs and Seller Contributions
VA buyers are not necessarily responsible for paying every closing cost themselves. Buyers and sellers may negotiate how certain allowable expenses will be paid. Subject to VA guidelines, a seller or builder may be able to provide credits toward allowable closing costs. The VA also permits certain seller concessions, generally limited to 4% of the property’s reasonable value. Closing-cost credits and seller concessions are treated differently under VA rules, so the purchase agreement and Loan Estimate should be reviewed carefully. The actual costs depend on the property, loan amount, location, lender and negotiated purchase terms.
VA Loans Are for a Primary Residence
A VA-backed purchase loan is intended for a home the eligible borrower plans to occupy as a primary residence. It is not designed to finance a vacation home or a property purchased solely for investment purposes. Military buyers should discuss anticipated orders, deployments and relocation timelines early in the mortgage process so the loan can be structured and documented appropriately.
Preparing for a VA Home Purchase
Military homebuyers often face circumstances that require additional planning, including deployments, PCS orders, changing duty stations and compressed relocation timelines.
Preparing early can help. Useful steps include:
- Requesting or confirming the COE
- Reviewing available entitlement
- Organizing income and service documentation
- Discussing deployment or relocation timing
- Reviewing credit and existing monthly debts
- Establishing a comfortable homebuying budget
- Accounting for closing costs and prepaid expenses
- Working with professionals familiar with VA transactions
- Identifying homes likely to meet VA property requirements
The goal is not simply to obtain a prequalification. It is to understand the full purchase process and prepare for potential timing, property and documentation issues.
Using a VA Loan More Than Once
The VA home loan benefit is not limited to a single use. Eligible borrowers may be able to use it more than once, depending on their available entitlement and whether entitlement from a previous VA loan has been restored. In some circumstances, a borrower may have more than one VA-backed loan at the same time. Existing VA loans, remaining entitlement, property disposition and occupancy plans must be reviewed individually.
VA borrowers may also have refinancing options, including an Interest Rate Reduction Refinance Loan for an existing VA-backed mortgage or a VA-backed cash-out refinance. Eligibility and financial benefit should be evaluated before refinancing.
VA Loan Frequently Asked Questions
Potentially eligible borrowers include Veterans, active-duty service members, certain National Guard and Reserve members, and qualifying surviving spouses. A Certificate of Eligibility confirms service-related eligibility.
The VA generally does not require a down payment. A lender or the circumstances of the transaction may require one, particularly when the borrower has partial entitlement or the purchase price exceeds the VA-determined reasonable value.
No, VA-backed loans do not require private mortgage insurance. Most borrowers pay a one-time VA funding fee, although certain eligible borrowers are exempt.
A seller may pay certain allowable closing costs and offer permitted concessions under VA guidelines. The amount and treatment depend on the type of expense and the purchase agreement.
Eligible gift funds may be acceptable for permitted expenses when the source and transfer are properly documented and all lender requirements are satisfied.
Yes, a VA-backed purchase loan is intended for a home that will serve as the borrower’s primary residence. It cannot generally be used to purchase a vacation home or a property held solely as an investment.
No, the VA appraisal evaluates value and applicable minimum property requirements. An independent home inspection provides a more detailed evaluation of the property’s condition.
Yes, the VA home loan guaranty is a lifetime benefit that may be used multiple times. Available entitlement and restoration requirements must be reviewed.
No, the COE confirms VA program eligibility based on service history and duty status. The borrower must still meet the lender’s credit, income, debt and underwriting requirements.
Explore Your VA Loan Benefit
VA financing can provide meaningful advantages, but eligibility, entitlement, funding fees, closing costs and occupancy rules must all be considered.
Platinum Mortgage can help you understand the VA loan process, request or review your Certificate of Eligibility, and compare VA financing with other available home loan options.
Contact Platinum Mortgage to discuss your homebuying plans and determine how your VA home loan benefit may help you move forward.
Thank you for your service.
All loans are subject to application, credit approval, property approval, available entitlement and applicable underwriting requirements. Program terms, interest rates, fees, loan limits and eligibility requirements are subject to change. This information is for general educational purposes and is not a commitment to lend. Platinum Mortgage is not affiliated with or acting on behalf of the U.S. Department of Veterans Affairs or any other government agency.